Book a demo

Every answer names its revision.

An AI knowledge assistant for CPA societies and compliance associations. Members get the revision their plan holds, cited to the page.

30 minutes, on your own publications.

Question: What changed in Publication 583 between tax years?

asked by all three
Helen Okoro, Tax practitioner, Premium

Between Rev. January 2021 and Rev. December 2024, the printed start-up cost limits differ, and a pointer moved:

Rev. Jan 2021
Printed up to $10,000 of start-up costs, reduced once they exceed $60,000 citation 1
Rev. Dec 2024
Prints up to $5,000, reduced once start-up or organizational costs exceed $50,000 citation 2
Amortizing
Pub. 535 chapter 7 citation 3 became the Instructions for Form 4562 citation 4
Unchanged
The periods of limitations in Table 3 read the same citation 5 citation 6
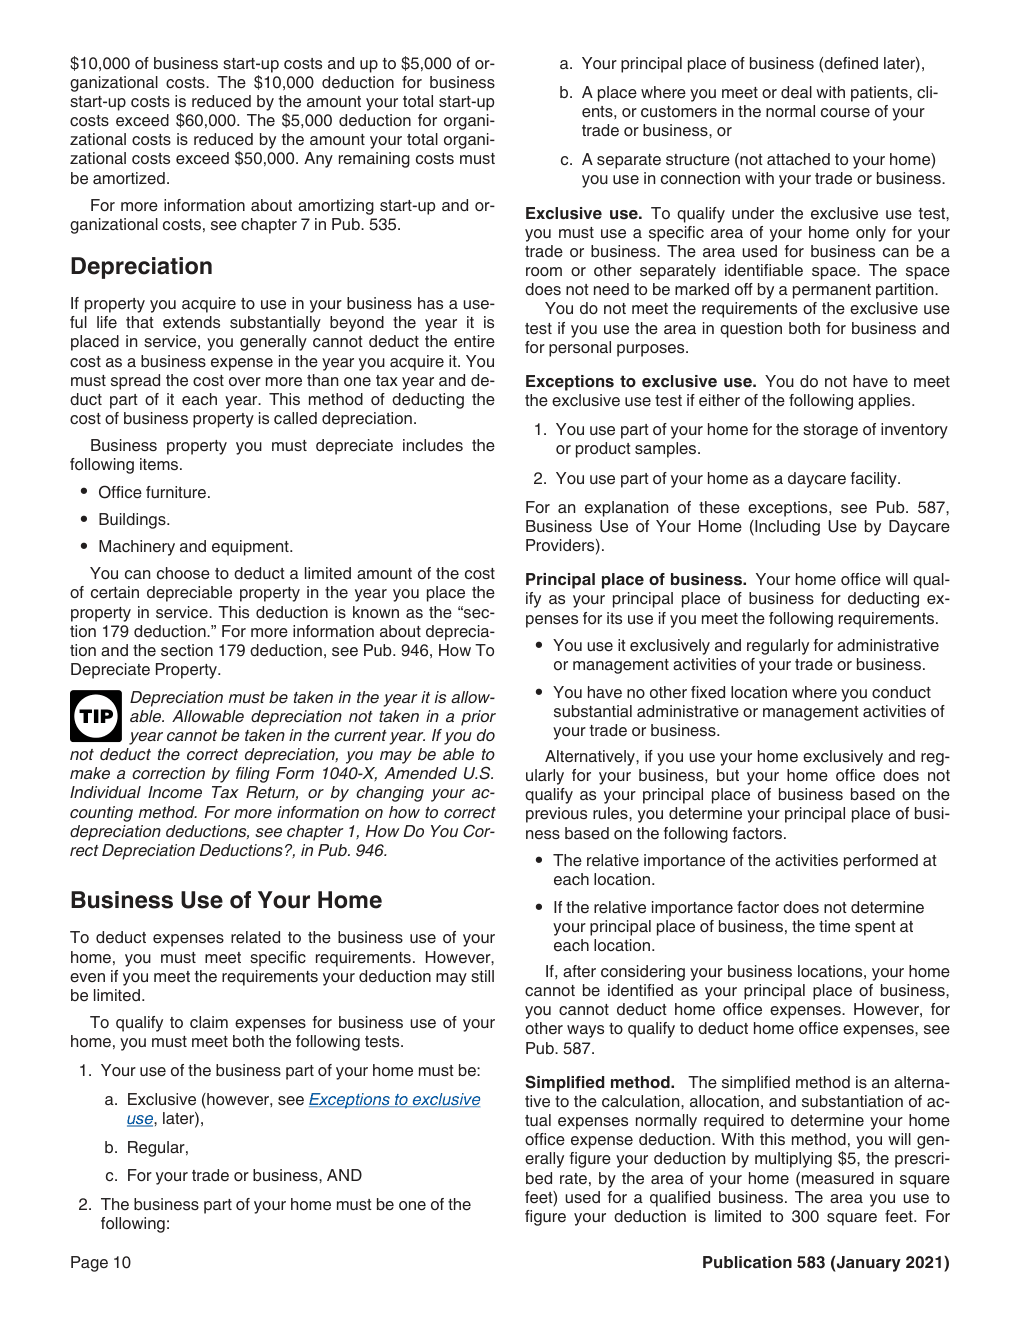
Publication 583, Rev. January 2021, page 10, with the start-up cost limits highlighted
1 · p.10
citation 1citation 3Pub 583 (2021)p.10citation 5p.15citation 2citation 4Pub 583 (2024)p.9citation 6p.15
3 tiers searched · 4 pages citedBoth revisions
Tomas Brandt, Small-business owner, Basic

Your plan holds the current revision, Rev. December 2024. The earlier revision is Premium content:

Start-up costs
Up to $5,000 of start-up costs and $5,000 of organizational costs, reduced once they exceed $50,000 citation 1
Amortizing
The Instructions for Form 4562 explain how citation 2
Not in tier
Rev. January 2021, the earlier revision, is Premium content
Publication 583, Rev. December 2024, page 9, with the start-up cost limits highlighted
1 · p.9
citation 1citation 2Pub 583 (2024)p.9Locked: Pub 583 (2021)
2 tiers searched · 1 page citedCurrent revision
Casey Lindqvist, Public visitor, Public
Not in your accessIRS Publication 583 is Basic content. The earlier revision is Premium content.
Request access

From the public recordThe IRS posts earlier revisions of its publications on IRS.gov. This library holds both revisions of Publication 583 side by side in the Premium tier.

Premium content · p.10
1 tier searched · 0 pages cited
Examples are built on public documents; access tiers are simulated.PublicBasicPremium

Each revision sits in the ring its subscribers pay for.

The 2021 revision lives on the Premium ring, so a Basic answer never quotes it.

Ask “What changed in Publication 583 between tax years?” as

Premium · locked for TomasBasicPublic
IRS Publication 583, Rev. December 2024Pub 583 (2024)
IRS Publication 15Pub 15 (2026)
IRS Publication 583, Rev. January 2021, locked
IRS Publication 946, locked
IRS Publication 463, locked
Searched 2 tiers · 2 documents
Tomas BrandtPartial match

Your plan holds the current revision, Rev. December 2024. The earlier revision is Premium content:

Start-up costs
Up to $5,000 of start-up costs and $5,000 of organizational costs, reduced once they exceed $50,000 citation 1
Amortizing
The Instructions for Form 4562 explain how citation 2
Not in tier
Rev. January 2021, the earlier revision, is Premium content
citation 1citation 2Pub 583 (2024)p.9Locked: Pub 583 (2021)
2 tiers searched · 1 page cited

What changed between revisions, page by page

Ask what changed. Chairlift opens both revisions at the passage and marks the difference.

  1. 2021Rev. Jan · on file
  2. 2024Rev. Dec · on file
  3. 2026today
Rev. Jan 2021p.10 · Business start-up costsPremium
Publication 583, Rev. January 2021, page 10, with the start-up cost paragraph and its limits highlighted
Rev. Dec 2024p.9 · Business start-up costsBasic
Publication 583, Rev. December 2024, page 9, with the start-up cost paragraph and its limits highlighted

Start-up costsChanged

Rev. 1-2021 printed $10,000 · $60,000becameRev. 12-2024 prints $5,000 · $50,000

The two revisions print different start-up cost limits

How to amortizeChanged

Pub. 535 ch. 7becameForm 4562 instr.

Where each revision sends you for amortizing start-up and organizational costs

Periods of limitationsUnchanged

2021 · 3 · 6 · 7 years; 2024 · the same three

Both revisions are IRS publications, shown as published. The highlights are added by this prototype.

Compliance tasks, drafted and held.

And no tax or legal advice from the library.

TSK-2026-0214 · Review customer due-diligence procedures

Requested from the Compliance module, an add-on outside the tiers. Nothing is created until Leon Abara, BSA officer, approves it.

  1. Done: Requested
  2. Done: Dry run
  3. Now: Approving
  4. Next: Approved
  5. Next: Created
task.createHarbor Trust compliance trackerTSK-2026-0214
titleReview customer due-diligence procedures
scopeRisk-based CDD policies, procedures and processesCDD-1
elementsCustomer risk profile, ongoing monitoring, beneficial ownership informationCDD-2
dueNov 13
requested_byMarguerite Dubois
Approve and create4 of 4 task elements

“How much tax will I owe this year?”

Rule P-03: refuse, and point to the return’s instructions.

“I can only answer from the Tax & Compliance Library, and it can’t work out what you owe.”
  • Your income, deductions and creditsWhat you owe turns on these, not on the library
  • IRS Interactive Tax AssistantIRS.gov/Help/ITA answers tax questionsPub. 583 p.2
  • A tax professionalA CPA or enrolled agent can work it through with you

0 passages that compute a personal liability · 0 answers made

30 minutes, on your own publications.

We map your tiers to rings and ask one question as three of your members.